


In July 2026, the domestic robotics industry recorded 52 financing events, with seed and angel rounds accounting for 44%. Shanghai led with 14 events, followed by Guangdong and Beijing. Notably, the core components sector saw 13 financing events, a 5.5% increase from June, indicating a growing focus on this area.
The rise in investment in core components is significant as it reflects a shift in capital allocation within the robotics industry. With 46% of the 13 component firms in later funding rounds, this suggests that some companies are entering a growth phase, positioning themselves for the next stage of productization and scale delivery.
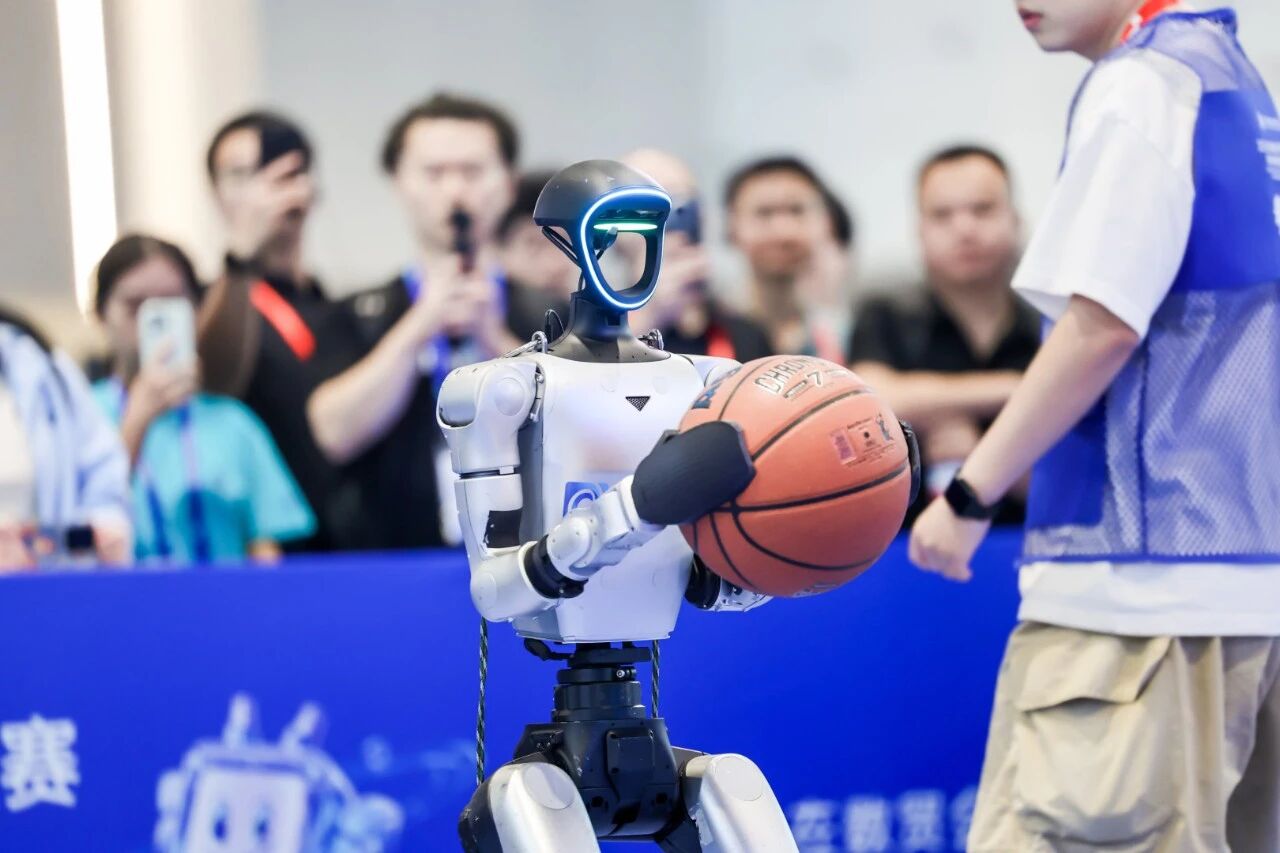
Looking ahead, the demand for upstream components such as sensors and specialized chips is expected to increase as humanoid robot manufacturers continue to secure funding. The financing events in July highlight a robust interest in tactile perception and joint execution technologies, indicating a strategic pivot towards core component autonomy in the robotics supply chain.
Editor's Note
The July investment trends in the robotics sector reveal a significant shift towards core components, which is crucial for the industry's growth. As companies secure funding for both humanoid robots and essential components, the competitive landscape is evolving. Enterprises should monitor these trends closely to align their procurement strategies with emerging technologies and market demands.












Leave a comment