

1. Executive Summary
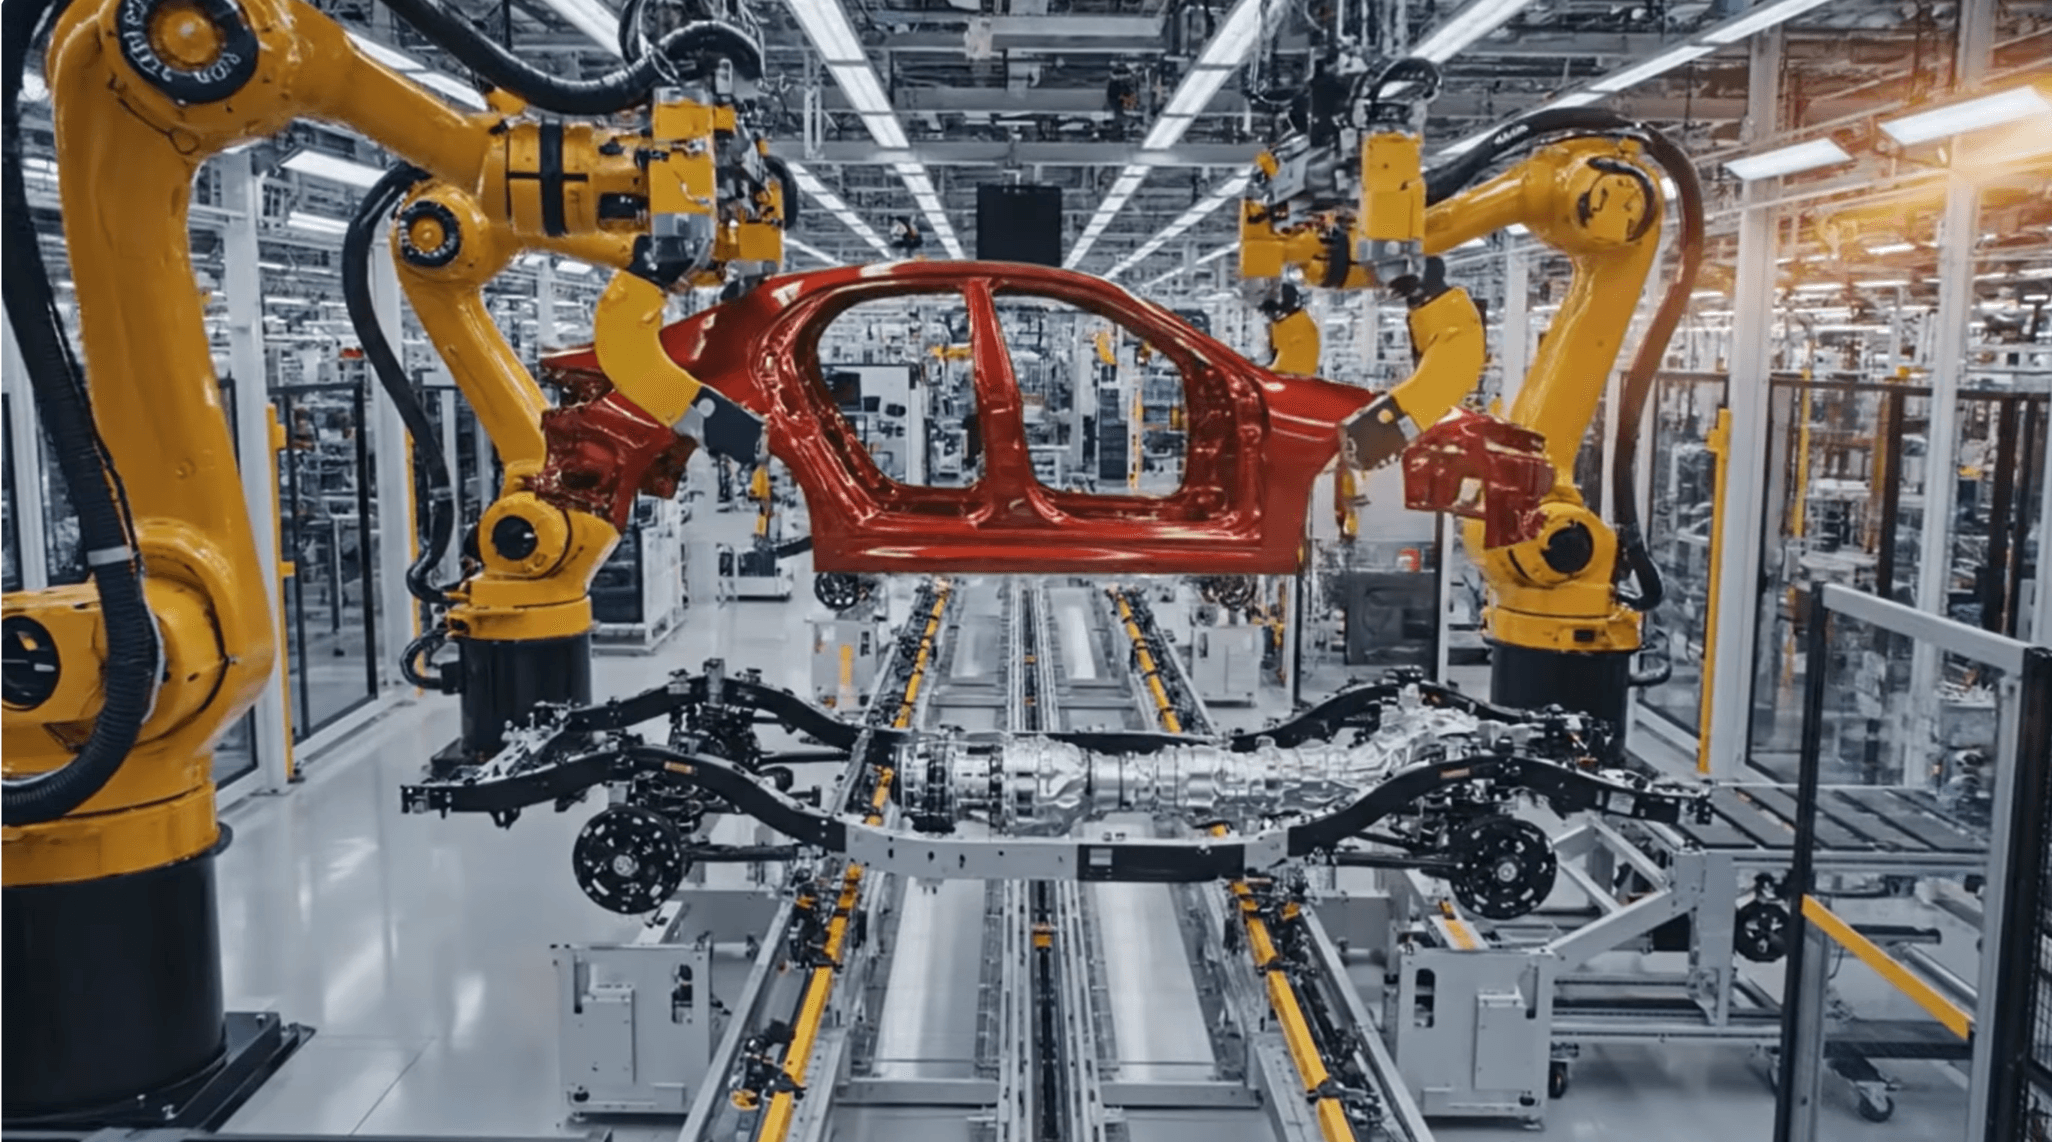
Industrial robotics is the foundational segment of the global robotics industry — the segment that, through six decades of refinement since Unimate first joined a General Motors line in 1961, has institutionalised the operating playbook the rest of robotics is now adopting. As of year-end 2024, more than 4.66 million industrial robots were operating in factories worldwide, with 542,000 new units installed during 2024 alone — the fourth consecutive year exceeding 500,000 annual installations. The category is mature, technologically standardised, and oligopolistic at the top, yet simultaneously experiencing one of the most consequential structural shifts in its history.
Three forces are reshaping the segment in 2025. First, electronics and electrical equipment overtook automotive as the world’s largest consuming industry for the first time in IFR’s record-keeping history — a structural milestone driven by the AI infrastructure build-out, semiconductor reshoring, and the EV battery cell wave. Second, Chinese domestic robot brands captured 57 percent of the China market in 2024, up from 28 percent a decade earlier, fundamentally reordering the global competitive landscape. Third, the United States is in the early innings of a CHIPS Act and Inflation Reduction Act-driven reshoring cycle that the Association for Advancing Automation expects will lift US industrial robot orders by mid-single digits annually through 2027.
From a US enterprise and investor perspective, this opening chapter establishes the boundaries, the consensus market size, the deployment base, and the deployment economics that frame the eight chapters that follow. The headline figures are straightforward: a global industrial robotics hardware market of 17.5 to 22 billion USD in 2025, expanding to 35 to 45 billion USD by 2030, with US installations stabilising in the 30,000 to 40,000 unit annual band and US robot density still less than one quarter of South Korea’s. The entire delta between those two density figures is the addressable opportunity for the US automation industry over the next decade.
2. ISO Definition and Scope Boundaries
The International Federation of Robotics applies the ISO 8373 definition: an industrial robot is an automatically controlled, reprogrammable, multipurpose manipulator with three or more axes, used in industrial automation. This definition has three working consequences for any market analysis. First, automatically controlled excludes teleoperated systems used in surgery, EOD, and undersea applications. Second, reprogrammable excludes hard-tooled fixed automation such as transfer lines and dedicated assembly machines. Third, three or more axes excludes simple linear pick-and-place modules. The definition deliberately straddles the line between manufacturing tools and autonomous systems.
Three boundary distinctions matter in practice. The first is industrial versus collaborative robots: cobots meet the ISO 8373 definition and are counted within IFR industrial statistics — they are not a separate category, but rather a subset characterised by ISO/TS 15066 power-and-force-limiting compliance. The second is industrial versus professional service robots: the dividing line is application context, not capability. A six-axis arm performing wafer handling inside a fab is industrial; the same arm performing room service in a hotel is service. The third is industrial versus humanoid robots: the IFR currently classifies humanoids as professional service robots in industrial settings, although several institutional analysts (Goldman Sachs, Morgan Stanley) treat humanoids as a separate emerging category.
3. Why 2025 Forecasts Diverge — $17.5B to $22B Explained
The most-cited 2025 figures from leading research firms span a range from approximately 17.4 billion USD (ABI Research) to 22 billion USD (Fortune Business Insights). The 25 percent spread is not a forecasting disagreement — it is a definitional one. ABI Research uses the narrowest hardware-only basis: only the manipulator unit and its controller. Fortune Business Insights and MarketsandMarkets include peripheral equipment (end-of-arm tooling, vision systems, safety enclosures) and integration revenue, which together can add 30 to 60 percent to the manipulator-only figure. GM Insights’ 17.78 billion USD 2024 figure, scaled forward at 13.3 percent CAGR, lands within ABI’s narrow definition. Buyers, integrators, and investors should explicitly anchor decisions to one definitional standard before comparing forecasts.
Institution | 2025 Estimate | 2030/2034 Forecast | CAGR | Scope Definition |
|---|---|---|---|---|
ABI Research | $17.4 B | $28 B (2030) | ~10% | Manipulator + controller only (narrow) |
GM Insights | $17.78 B (2024) | $60.1 B (2034) | 13.3% | Manipulator + controller (narrow) |
Fortune Business Insights | $22 B | $45 B (2030) | 12% | Includes peripherals + EOAT |
MarketsandMarkets | $21 B | $41 B (2030) | 12% | Manipulator + peripherals + integration partial |
Consensus Range | $17.5–22 B | $35–45 B | 12–13% | Anchor: ABI for narrow; FBI for broad |
The implication for strategic planning is that hardware-only growth (10 to 13 percent) substantially understates the value-chain growth (15 to 18 percent), because peripheral, integration, software, and service revenues are growing faster than the manipulator itself. Chapter 5 of this series quantifies the components share, and Chapter 6 quantifies the software-and-digital-twin share, which together account for 60 to 65 percent of total system value at the point of plant deployment.
4. Global Installation History 2018–2024
The seven-year history shown below is the foundational data series for any industrial robotics analysis. Two patterns dominate. First, the segment has institutionalised a 500,000+ annual installation floor — even through the COVID demand shock of 2020, the trough held at 384,000 units, and recovery exceeded 2019 levels by 2021. Second, the operational stock has compounded at roughly 12 percent annually — meaning the installed base is the durable economic footprint, while annual installations capture the marginal demand.
Year | New Installations | Operational Stock | Top Industry | YoY Growth |
|---|---|---|---|---|
2018 | 422,000 | 2,439,000 | Automotive | +6% |
2019 | 373,000 | 2,722,000 | Automotive | −12% |
2020 | 384,000 | 3,015,000 | Electronics | +3% |
2021 | 517,000 | 3,477,000 | Electronics | +31% |
2022 | 553,000 | 3,904,000 | Electronics | +5% |
2023 | 541,000 | 4,281,000 | Automotive | −2% |
2024 | 542,000 | 4,664,000 | Electronics (1st time) | +0.2% |
The 2024 milestone deserves emphasis: electronics and electrical equipment installed 128,899 industrial robots globally, surpassing automotive’s 126,088 — the first time in IFR’s record-keeping that automotive was not the leading consuming industry. The driver is a structural one: AI server manufacturing, advanced node semiconductor fabs, and consumer electronics reshoring are collectively absorbing more SCARA, six-axis, and clean-room robots than the automotive industry, which is simultaneously navigating the EV transition with reduced cycle complexity. This rotation will likely deepen through 2027.
5. United States Market Position
The United States installed 34,200 industrial robots in 2024, ranking third globally behind China (276,288) and Japan (44,069). US installations declined 9 percent from 2023, reflecting two cyclical headwinds — automotive consolidation around the EV transition and tightened capital expenditure approval cycles — partially offset by accelerating semiconductor and EV battery investments. The Association for Advancing Automation reports that US industrial robot orders rose 4.3 percent in the first half of 2025 versus the same period of 2024, with growth led by automotive, electronics, and food and beverage.
The structural opportunity is significant: US robot density stands at approximately 295 robots per 10,000 manufacturing workers, ranking ninth globally. South Korea leads at 1,012 per 10,000; Singapore is 770; Germany is 429; Japan is 419; China reached 470 in 2024. To match South Korea’s density, the United States would need to add approximately 1.5 to 2.0 million additional industrial robots — a multi-decade upgrade cycle that the CHIPS Act, IRA, and onshoring policy framework are explicitly designed to accelerate. This addressable upside, more than any short-term cyclical signal, is the strategic story of US industrial robotics through 2030.
6. Detailed Anchor Cases — Global Industrial Robot Deployments
The four cases below profile representative deployments across four major geographies — the United States, Europe, China, and Japan — each illustrating a distinct application archetype and factory economics model. Cases were selected for geographic representation, deployment scale, and quality of public ROI disclosure.
Case 1 — Ford Motor Company × Michigan Assembly Operations
Dimension | Detail |
|---|---|
Background | Ford operates approximately 20,000 industrial robots across its global manufacturing footprint, with the largest US concentration at Dearborn Truck Plant (MI), Kentucky Truck Plant, and the new BlueOval City EV complex (TN). Body-shop welding density at Dearborn exceeds 1,200 robots per assembly line, primarily FANUC and KUKA six-axis platforms. |
Deployment Scale | Ford’s 2023–2025 capital plan committed 50 B USD globally to EV transition, of which an estimated 8 to 10 B USD is dedicated to manufacturing equipment including new robotic welding lines for the F-150 Lightning, Mustang Mach-E, and the BlueOval battery JV (with SK On). The new Rouge Electric Vehicle Center alone houses over 700 new-installation robots across body and battery-pack assembly. |
ROI Data | Ford does not disclose plant-level ROI; however, sector benchmarks from Boston Consulting Group place body-shop robot payback at 18 to 30 months, with cycle-time improvements of 25 to 40 percent versus prior generation tooling. Ford’s Spot quadruped robot deployment (Boston Dynamics) at Dearborn for laser-scan inventory of plant infrastructure cut survey time by 50 percent and is in service across multiple plants. |
Case 2 — Volkswagen Group × Zwickau EV Plant (Germany)
Dimension | Detail |
|---|---|
Background | Volkswagen’s Zwickau plant (Saxony, Germany) is Europe’s largest dedicated battery-electric vehicle factory, fully converted from ICE production in 2020. The plant produces the ID.3, ID.4, and ID.5 across six model variants on a single production line. VW Group operates approximately 13,000 robots across its German manufacturing network; Zwickau alone runs over 1,700 robot units post-conversion, supplied primarily by KUKA (welding and body shop), ABB (paint shop), and FANUC (press shop). |
Deployment Scale | VW invested approximately 1.2 B EUR in converting Zwickau from ICE to EV production, of which an estimated 400 to 500 M EUR was directed to new robotic welding and assembly lines. Body-shop welding automation rate exceeds 95%. Annual capacity stands at 330,000 EVs across two shifts with 8,000 employees, yielding a robot density of approximately 2,100 units per 10,000 workers — among the highest in European automotive manufacturing. The multi-model flexible line handles six variants without a dedicated retooling stop. |
ROI Data | VW disclosed that the Zwickau conversion achieved a 30% reduction in body-shop cycle time versus the prior Golf platform. KUKA reports that the high-mix welding cells reduced changeover time from 4 hours to under 15 minutes. Weld-quality defect rates dropped 45% versus manual operations. VW’s 2024 Annual Report indicates Zwickau achieves production cost per unit approximately 18% below the Group’s average ICE plant benchmark, primarily attributable to automation density. BCG estimates European automotive body-shop robot payback at 18 to 24 months at Zwickau-class utilisation rates. |
Case 3 — BYD × Shenzhen Pingshan Manufacturing Base (China)
Dimension | Detail |
|---|---|
Background | BYD (Build Your Dreams) is China’s largest new energy vehicle manufacturer and the world’s top EV seller by volume in 2024, delivering 1.76 million pure-battery EVs and 3.42 million NEVs in total. BYD’s Shenzhen Pingshan campus spans over 10 million sqm and serves as the group’s manufacturing and R&D headquarters. BYD’s automation strategy combines international suppliers (ABB, KUKA, FANUC) with domestic vendors (Estun, Siasun, Inovance), with domestic robot share exceeding 40% by 2024 — a deliberate supply-chain localisation policy. |
Deployment Scale | BYD’s 2024 investor communications disclose over 30,000 industrial robots deployed across its manufacturing network (Shenzhen, Xi’an, Zhengzhou, Changsha, and overseas plants). The Shenzhen Blade Battery production line operates at a 96%+ automation rate, requiring fewer than 300 workers per GWh of annual capacity. Over 2023 to 2024, BYD invested approximately 35 B CNY (approx. 4.8 B USD) in manufacturing equipment, with an estimated 30 to 40% share directed to robotic systems. BYD’s robot density reached approximately 470 units per 10,000 workers by end-2024 — above China’s national average and approaching Germany’s 429. |
ROI Data | China Securities Research (2024) estimates BYD’s automation investment reduces cell-to-pack assembly labour cost by approximately 60% versus the industry average, with battery busbar weld defect rates below 50 ppm. BYD’s NEV segment gross margin expanded from 15.8% (2022) to 23.0% (2024), with manufacturing automation credited alongside scale as a primary driver. Payback period on robotic welding and assembly equipment is estimated at 18 to 24 months at BYD’s current volume. The domestic-vendor strategy further reduces total cost of ownership by an estimated 15 to 20% versus equivalent imported platforms. |
Case 4 — Toyota Motor × Motomachi Plant, Toyota City (Japan)
Dimension | Detail |
|---|---|
Background | Toyota Motor Corporation operates approximately 36,000 industrial robots across its global manufacturing network, with Japan accounting for approximately 14,000 units across 14 domestic plants. The Motomachi Plant (Toyota City, Aichi Prefecture) is Toyota’s flagship advanced-manufacturing facility, producing the Mirai fuel-cell vehicle and Lexus LC/LC-F. Toyota’s robot philosophy is distinctive: the company deliberately limits full automation in certain assembly operations under its jidoka (autonomation) principle, deploying collaborative robots alongside human workers to augment — not simply replace — craft skill. Robot suppliers include FANUC, Yaskawa, and ABB, alongside Toyota’s in-house T-HR3 research platforms. |
Deployment Scale | Toyota invested approximately 800 B JPY (approx. 5.4 B USD) in domestic manufacturing capex over 2022 to 2024. The Motomachi 2023 renovation added approximately 900 new robotic cells including FANUC welding robots, ABB paint robots, and 320 collaborative robots (FANUC CRX series) for final assembly. The Takaoka Plant (GR86 and Crown production) operates 1,100 welding robots at 92% body-shop automation, while final assembly retains a human-to-robot ratio of approximately 1:1. Toyota’s Global Production Center (Toyota City) validates all robotic cell configurations before deployment to 28 overseas plants across 9 countries. |
ROI Data | Toyota’s 2024 Sustainability Report discloses that collaborative robots in final assembly reduced ergonomic injury rates by 68% over 2019 to 2024 and increased production mix flexibility by 22% without full line retooling. The Motomachi paint-shop robotic renovation achieved a 32% reduction in paint consumption and a 28% reduction in energy consumption versus the prior system. Toyota’s kirakira (sparkle) inspection system — combining robotic camera arrays with AI defect detection — cut final-inspection headcount by 40% while improving defect escape rate by 55%. Toyota estimates overall robot-related productivity improvement at approximately 15% annually in renovated facilities, with payback on collaborative robot cells at 24 to 36 months. |
7. Five-Year Outlook 2025–2030
The base case across institutional forecasts converges on global industrial robot installations exceeding 700,000 units annually by 2030, with the operational stock approaching 7 million units. Three structural shifts will define the period. First, electronics will solidify its lead over automotive — by 2027, electronics is expected to account for over 30 percent of global installations versus automotive’s 22 percent. Second, China’s domestic supplier share is expected to exceed 65 percent of its home market, reshaping global pricing. Third, US installation volume is projected to recover to the 40,000 to 45,000 unit band by 2027 as CHIPS-funded fabs and IRA-funded battery plants enter equipment-installation phases.
For US enterprises, the strategic priorities through 2030 are clear: deepen software and integration capability where US firms hold genuine advantage; explicitly evaluate Chinese hardware where regulation and end-customer requirements permit; treat robot density gap versus South Korea and Germany as a multi-decade addressable upside, not a defect. The eight chapters that follow drill into each of these dimensions in detail.
Sources: IFR World Robotics 2025 · ABI Research Commercial & Industrial Robotics 3Q 2025 · Fortune Business Insights · MarketsandMarkets · GM Insights · A3 Association for Advancing Automation · Company filings (Ford Motor, Volkswagen Group, BYD, Toyota Motor) · Boston Consulting Group manufacturing automation benchmarks · China Securities Research 2024 · Toyota Sustainability Report 2024









Leave a comment